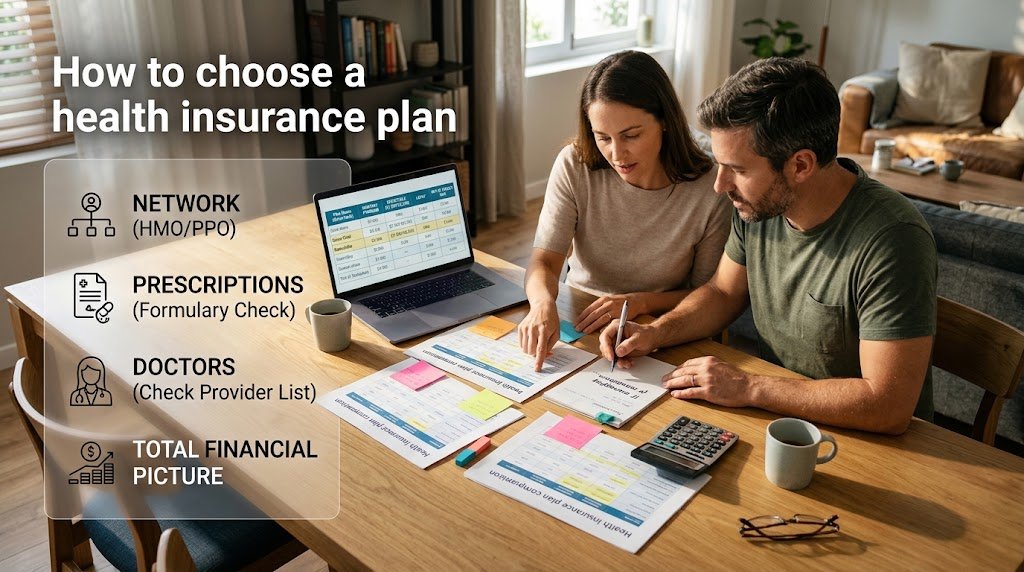
How to choose a health insurance plan
There is a type of fear that appears every year during open enrollment. You live your life, then suddenly there is a deadline and a wall of plan names that all blur together. Silver, gold, bronze, HMO, PPO, and you are expected to choose one before the window closes.
Here is the part that really helps. There is no secret plan hidden out there waiting to be found. The whole game is about matching a plan to your situation, and once you know what to focus on, this stops feeling so overwhelming.
Why A Small Premium Can Still Cost You More
Most people go for the premium plan and think they are finished. That makes sense, since that is the number you see every month, so it feels like the one to lower.
That number tells only half the story. A plan that advertises a premium might have a deductible of around $7,000, which means you pay thousands out of pocket before insurance coverage begins. If you are someone who sees doctors often. You are managing a long‑term health condition; that “budget‑friendly” plan can end up costing far more over the course of a year than a higher-premium plan that covers more at the outset.
The better move is to look at the financial picture, not just one number. Premium matters, yes. Also, your deductible, your copays, coinsurance, and the out‑of‑pocket maximum, which is the ceiling on how much you would pay even in the worst possible year.
Get Honest About How You Use Healthcare
Before you even open a comparison chart, take a minute to think about your real habits. Are you at the doctor often? Do you show up once a year for a checkup? Is there a condition you manage that needs regular attention? Are you on any prescriptions now?
If medication is part of your routine, check the plan’s formulary, its official list of covered drugs, before assuming everything you take is covered. Drugs are sorted into pricing tiers, and something that is cheap under one plan can suddenly cost a lot more under a plan that looks almost the same on the surface.
The same logic applies if therapy, mental health care,e or maternity coverage matter to you. Confirm those benefits directly rather than assuming they are standard, because coverage quality here varies more between plans than most people expect.
What’s Different About Enrolling This Year
If you have stuck with the same plan for years and were planning to click renew without looking, this year is worth slowing down for. Premiums are expected to rise for many people on Marketplace plans heading into 2026. The enhanced subsidies that helped make coverage more affordable are set to expire after 2025.
In words, a plan that fit your budget comfortably last year might look completely different this time, even if your health and income have not changed at all. It is worth running the numbers rather than assuming last year’s decision still holds up.
Missing The Deadline Costs You More Than You’d Expect
Enrollment windows are not open year-round, which can catch people off guard. For individuals, the window to lock in 2026 coverage opens in late fall 2025. If you miss that window, you are generally out of luck unless you qualify for a Special Enrollment Period.
Those special windows open after life events such as losing coverage through a job, getting married or divorced, having a baby, or moving somewhere new. If one of those hits your life, you usually have around 60 days from that event to enroll, so it is worth moving quickly rather than assuming you can get back to it whenever.
Your Actual Life Should Shape This Decision, Not A Generic Checklist
Broad advice can only take you so far because health insurance needs change dramatically depending on where you are in life. Someone who just turned 26 and was removed from a parent’s plan is dealing with a different situation than someone who recently went freelance or someone who is moving closer to retirement before Medicare starts.
Instead of chasing one universal formula, it is much better to sit with your own situation. Consider your income range, whether you are covering yourself or an entire family, how predictable your health‑care needs are, and realistically how much you can afford each month versus how much you could absorb if an unexpected event occurs. Choosing a health insurance plan is about these details, not a one‑size‑fits‑all answer.
Bottom Line
There is no health insurance plan that you can find because such a plan does not exist. What you’ll find is a plan that truly fits your life, health habits, budget, and risk tolerance. Do not choose the option with the lowest monthly premium. Take a few minutes to compare deductibles, verify that your medications and doctors are covered, and keep track of enrollment deadlines. That small effort now can save you money and reduce a lot of stress later. Choosing a health insurance plan is easier when you pay attention to these factors.
References:
- National Association of Insurance Commissioners. What Are My Health Plan Options for 2026?
- NewHealthInsurance. Choosing the Best Health Insurance for 2026
- NewHealthInsurance. How to Choose the Best Health Insurance Plan for 2026
- [AHiX. 2026 Health Insurance Guide by Life Situation](https://www.ahix.com/blog/2026-health-insurance-guide-, by-life-situation/)
