The Right Amount Of Life Insurance
Most people buy life insurance the same way they pick a Wi-Fi password: quickly, based on whatever number sounded reasonable at the time, then never think about it again. Someone tells them, “Get ten times your salary,” and that’s the end of the research. No spreadsheet, no real math, just a round number that felt safe enough.
The problem is that generic rule often leaves families underinsured exactly when it matters most, according to financial planners who work with this stuff daily. So let’s break down how to land on a number that fits your situation, rather than just borrowing someone else’s guess.
Why The “10 Times Income” Rule Isn’t Enough
You’ve probably heard this one. Multiply your annual income by ten, and that’s your coverage number. It’s simple, which is exactly why it spread so widely, but simple doesn’t always mean accurate.
According to NerdWallet, this rule doesn’t actually account for your family’s specific needs, existing savings, or any life insurance you might already have through work. It also completely ignores stay-at-home parents, who absolutely need coverage, even without a paycheck in their name.
Financial planning firm Greenbush Financial Group points out something worth sitting with: even a coverage shortfall of $250,000 can force a family to sell their home, drain retirement savings, or pile up debt during one of the hardest periods of their lives.
Some advisors use a wider range based on age rather than a flat multiplier. Guardian Life suggests scaling the multiple based on age, something closer to 30 times your income in your 20s and 30s, gradually dropping to around 10 times your income by your early 60s, since your remaining working years shrink as you get older.
What Actually Goes Into The Real Number
If a flat multiplier isn’t reliable enough, what should you actually be calculating? A few consistent factors appear in every serious guide on this topic.
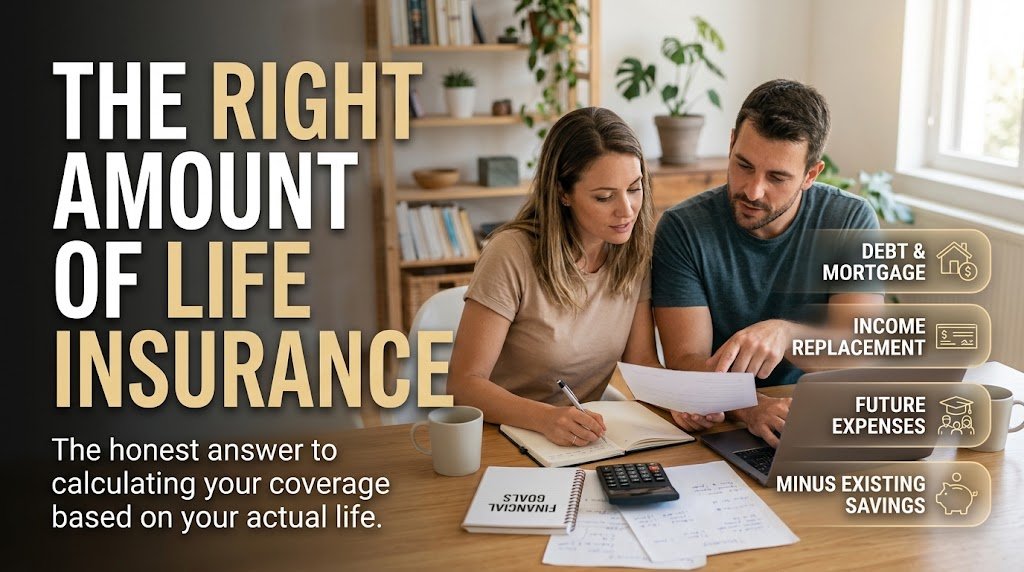
Income replacement. How many years would your family need your income replaced if you weren’t there anymore? This is usually the biggest single piece of the calculation.
Outstanding debt. Mortgage balance, car loans, credit cards, anything that wouldn’t just disappear if you passed away.
Future expenses. College costs for kids, childcare if you have a stay-at-home partner, and even funeral or final expenses.
Existing savings and coverage. Retirement accounts, workplace life insurance, anything that would already cushion the gap.
The National Association of Insurance Commissioners specifically recommends looking at who actually depends on your income, rather than treating income alone as the whole answer. Two people earning the exact same salary can have completely different real-world needs depending on debt, dependents, and financial goals.
Term Versus Whole Life, In Plain Terms
Once you know roughly how much coverage you need, the next decision is what type of policy actually gets you there.
Term life insurance covers you for a set period, usually somewhere between 10 and 30 years, and pays out only if you pass away during that window. It’s significantly cheaper than permanent coverage, which is exactly why most financial experts recommend it for the average family.
Whole life and other permanent policies don’t expire and build cash value over time, but they typically cost five to fifteen times more than an equivalent amount of term coverage. For most households, that math doesn’t work in their favor, though permanent coverage can make sense in specific estate planning situations for wealthier individuals.
A healthy person in their early 30s can often lock in a million dollars of term coverage for well under fifty dollars a month, and rates generally climb the longer you wait, so buying earlier tends to work out cheaper over the life of the policy.
The Real Cost Of Waiting
Here’s the uncomfortable part. Roughly 42 percent of American adults currently have no life insurance, according to industry research compiled by insurance analysts. That leaves an enormous financial gap, one estimated to exceed 12 trillion dollars nationally, sitting behind families who assumed they had more time to figure it out.
Nobody plans around a sudden diagnosis or an unexpected accident. That’s exactly the point of life insurance in the first place; it’s not there for the scenario you expect, it’s there for the one you didn’t see coming.
So What Should You Actually Do
Start by running real numbers instead of guessing. Add up your outstanding debt, estimate how many years of income your family would need replaced, factor in future costs like education, then subtract whatever savings or existing coverage you already have. That gives you a starting figure grounded in your actual life, not a generic rule pulled from a random blog post.
From there, term life insurance is usually the most practical starting point for most people, especially younger families juggling a mortgage and kids. If your finances are more complex, involving estate planning or long-term wealth transfer, it’s worth sitting down with a licensed financial advisor who can walk you through options suited to your specific situation.
The number doesn’t need to be perfect on the first try. It just needs to be based on your actual life, not someone else’s rule of thumb.
You must read to get info about fitness.
Source
